Why the US backs UK venture debt, and UK investors don’t
US credit funds engage faster with UK venture debt than British investors do. We look at why, where the bottlenecks sit and what the UK should ask itself.
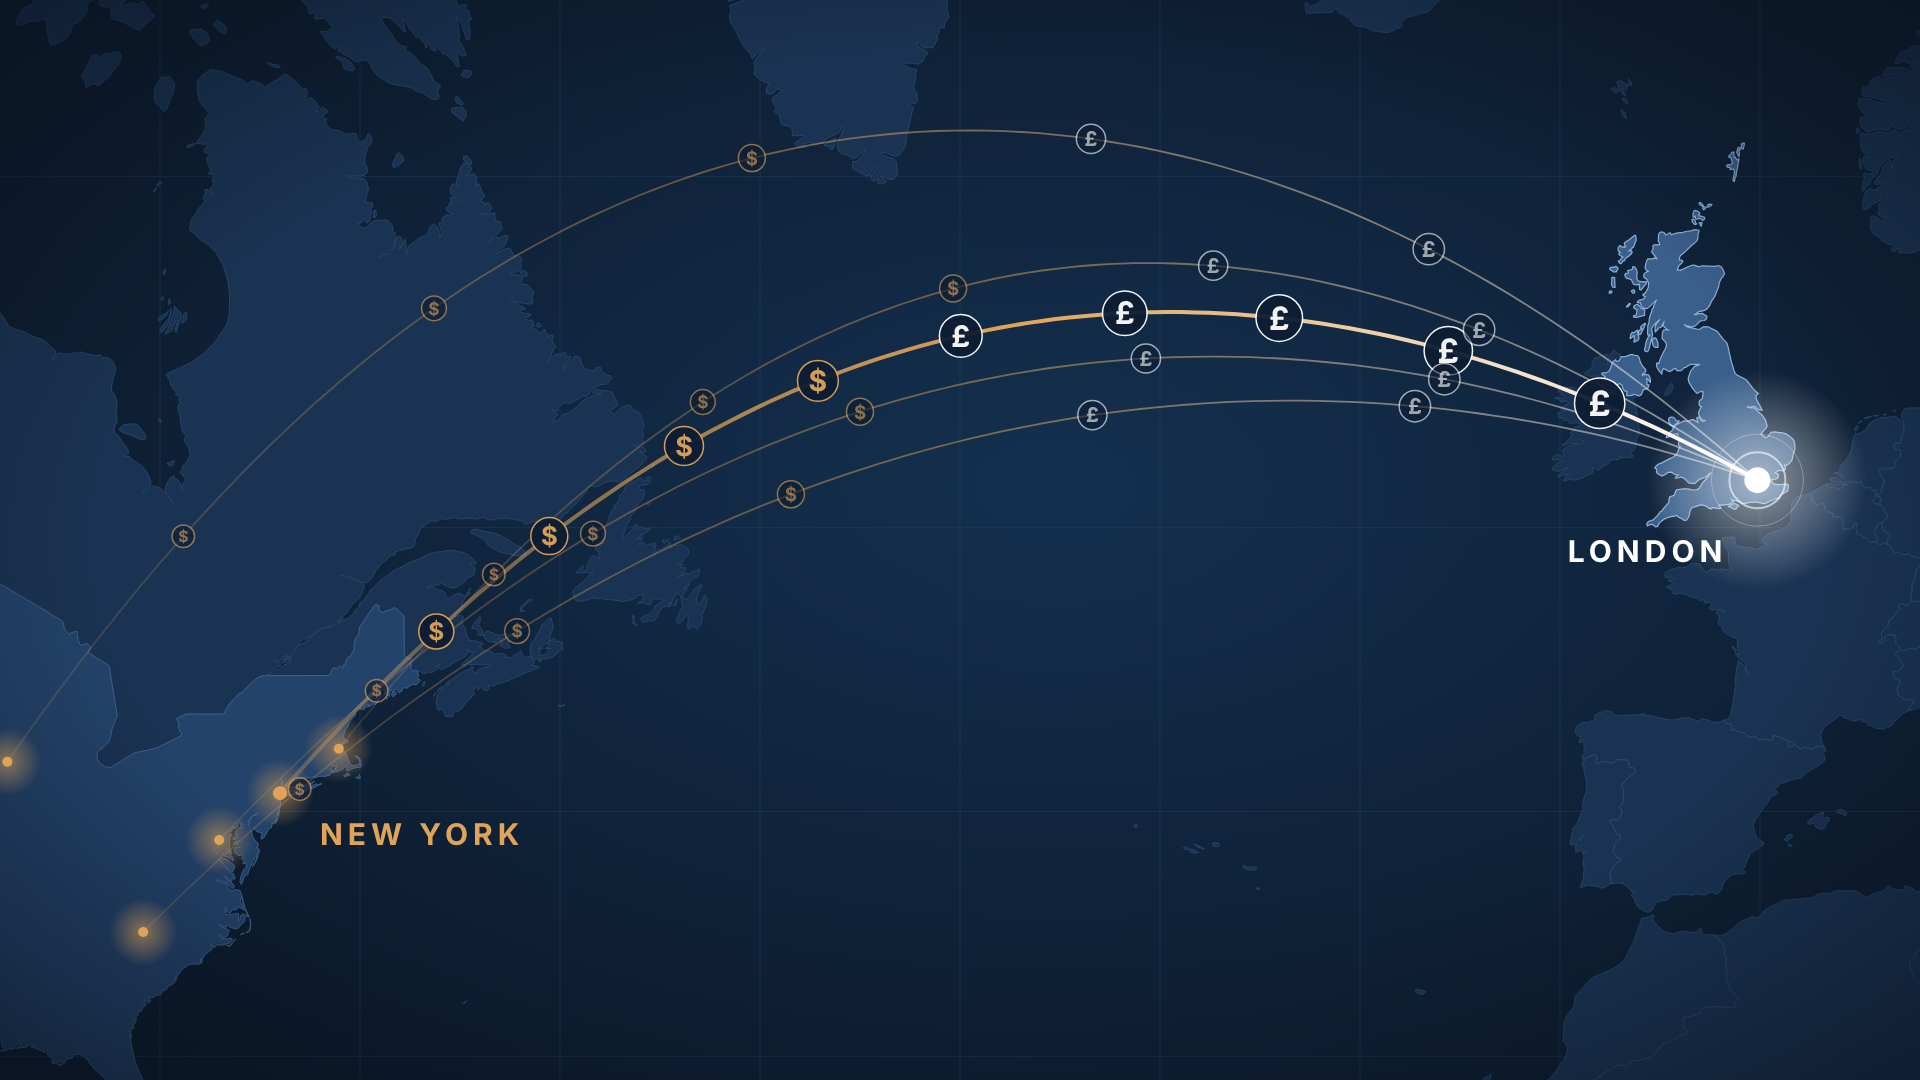
Nighthawk lends to UK tech businesses, yet the capital most willing to fund that lending keeps arriving from America.
Key points
- US credit funds engage faster and more deeply with UK venture debt than their British counterparts.
- The BBB's new £450m venture debt product is a significant step, but details are still to come.
- UK pools of capital are structurally pointed away from venture debt, creating five bottlenecks.
- US investors understand venture debt as an asset class and price it on its merits.
- A UK lending market funded from abroad is a market whose capacity is set abroad.
When we talk to investors about our UK venture debt book, US credit funds engage faster and more deeply than their British counterparts. That is striking, because the UK has a development bank working on exactly this gap — the British Business Bank (BBB) — and it has just made its biggest move yet into venture debt. The US has no single equivalent, yet its investors still turn up first.
This piece sets out why we think that happens, where the bottlenecks sit, and the questions the UK should be asking itself.
This isn't theoretical for us. Nighthawk's first venture debt joint venture is with a US credit fund, and the most meaningful interest in what comes next has also come from the US. We lend in Britain to British companies; the capital to do it is coming from across the Atlantic.
Policy is moving in the right direction
The UK has never had more policy aimed at domestic growth capital. The challenge is turning it into UK money for UK lenders.
The policy stack is substantial:
- British Business Bank: total financial capacity raised to £25.6bn at the 2025 Spending Review, with annual investment rising by about two-thirds to c.£3.5bn.
- Mansion House Accord (May 2025): 17 DC providers pledged 10% of default assets to private markets by 2030, half of it in the UK.
- Pension consolidation: larger DC and LGPS pools intended to give schemes the scale to invest in private assets.
Then came the most significant step for our market. The Autumn Budget 2026 committed £450m to a new BBB venture debt product, "filling a gap in the UK's financing landscape for innovative scale-ups". The BBB will work with commercial lenders to unlock facilities, with Industrial Strategy sectors such as defence and dual-use tech in focus.
This deserves real credit. It recognises venture debt as a distinct asset class, puts serious money behind it, and commits to working through the lenders already in the market. Details are still to come, which is an opportunity: designed well, it could be the catalyst that finally brings UK institutional capital alongside.
The UK is also not short of venture debt demand. UK companies took 41% of European venture debt deals and 34% of capital in 2025 — roughly €6.7bn. The question is who funds the lenders.
The US, by contrast, has no BBB. But it would be wrong to say it has no intervention. The SBA's SBIC programme lets licensed private funds borrow government-guaranteed debentures at up to 2x their private capital, up to $250m per fund after the Investing in All of America Act (May 2026). The difference is design: the US subsidises leverage for private managers and lets the market pick, rather than acting as an LP itself.
Where the UK bottlenecks sit
The UK's large pools of capital are structurally pointed away from venture debt, which is why the BBB's role as an anchor matters so much.
| Pool | Size | Why it rarely reaches UK venture debt |
|---|---|---|
| DB pensions | £1.13trn assets, 123% funded (Mar 2026) | Mature, liability-matched and heading for insurer buyout. Gilts and investment-grade credit, not unrated growth loans. |
| Bulk annuity insurers | Absorbing DB buyouts | Matching adjustment rules reward predictable, rated cash flows. Venture debt fits poorly. |
| DC default funds | £334bn tracked by Accord signatories | 3.3% in UK private markets at end-2025, mostly property (£8.0bn). UK private debt and credit: £0.9bn — under 0.3% of assets. |
| LGPS pools | Consolidating | Rising minimum tickets squeeze out lower and mid-market funds. |
| UK HNW and wealth | Large, fragmented | Tax reliefs (EIS, SEIS, VCT) reward equity. There is no equivalent incentive to lend. |
Five bottlenecks follow from this:
- Scale mismatch. Venture debt funds typically raise £100m–£300m. Consolidated pension pools want tickets that would make them most of the fund, so they default to the largest credit managers.
- Asset-class orphan. Venture debt is too risky for credit buckets and too low-returning for venture buckets. UK allocators rarely have a dedicated slot for it, so it is rarely priced on its own terms.
- Anchors need co-investors. The BBB does its job by bringing private investors in alongside it, so a manager still needs commercial money to close. The Salica Growth Debt Fund II close shows the model working — £30m from the BBB matched by £30m from West Yorkshire Pension Fund. We need more UK pension funds to follow.
- Fees, charge caps and liquidity. DC charge caps, daily dealing and inconsistent cost disclosure make any private strategy harder to hold. A newer, smaller asset class suffers most.
- Career risk and herding. UK trustees are rewarded for following peers, and in UK venture debt there are almost no peers to follow.
Some things are moving
There is some real progress on UK venture debt, but it remains the exception.
Pension money in UK venture debt
A small amount of pension money has found its way into UK venture debt. It is a great start.
BBB venture debt product
£450mAnnounced in the Autumn Budget 2026. A clear signal that government and the BBB see venture debt as part of the answer for UK scale-ups.
Two data points are not yet a market, but the direction is right — and the £450m product could turn them into the norm.
What draws US capital in
US investors already understand venture debt as an asset class, and they price it for what it is.
A US credit fund looks at a senior secured loan to a VC-backed business and prices the risk and the return on their merits.
That is the heart of it. A US credit fund looks at a senior secured loan to a VC-backed business and prices the risk and the return on their merits: a credit return with credit protections, plus warrant upside. UK investors too often do neither. Some demand equity-like returns; others treat it as unrated credit and walk away. Five factors sit behind the US approach:
- Twenty years of data. US venture debt reached a record $68.8bn in 2025, against c.€20.1bn for all of Europe. Listed BDCs publish quarterly loan-level data, and third-party indices track losses back to 2005. A US investment committee can benchmark a UK manager; a UK committee often has nothing to benchmark against.
- A dedicated bucket. US credit investors treat growth lending as an established strategy, with specialist funds, listed BDCs and dedicated teams. It sits in the credit allocation and is judged as credit.
- Diversification out of a crowded home market. Europe's share of LP private credit fundraising rose from 20.4% in H1 2024 to 32.4% in H1 2025, as US direct lending looked saturated. Managers cite a net return premium of c.100bps for Europe. UK venture debt offers that premium with English law, familiar documentation and fewer competing lenders.
- Government-backed leverage at home. SBIC debentures let US managers enhance returns with cheap, guaranteed leverage. US LPs are used to the state underwriting the manager's returns, not sitting beside them as an LP.
- Valuation. UK tech assets trade at a discount to US peers. For a lender, lower entry valuations and less competition can mean better structure and pricing for the same credit risk.
Our own experience fits this pattern: the US fund behind our first JV understood the asset class from day one and did not need a UK track record to be built from scratch.
Why it matters
US capital is welcome, but a UK lending market funded from abroad is a market whose capacity is set abroad.
- Cyclicality. Overseas LPs allocate to the UK at the margin. When the dollar, US rates or US sentiment turn, the UK is the first allocation trimmed.
- Value leakage. Returns on lending to UK companies — interest, fees and warrants — accrue to US investors, not UK savers.
- Policy reach. BBB support goes furthest when UK capital comes in alongside it. Without that, more of the return from backing British companies ends up overseas.
- Founder cost. Thin domestic lender capacity means less competition on terms and more dilutive equity rounds for UK founders.
Questions the UK should be asking
Thirteen questions, grouped by who should answer them.
For HM Treasury and the BBB, as the £450m product takes shape
- Could elements of the US SBIC model — leverage that lets specialist lenders scale — help the £450m go further?
- How can the product be designed to crowd in UK pension and insurance capital alongside it, not just overseas money?
- Would the BBB take a first-loss or cornerstone position large enough to let a debt fund reach first close without waiting for a commercial anchor?
- Why do equity investors get EIS, SEIS and VCT relief while lenders to the same companies get nothing?
For pension schemes and consultants
- Where does venture debt sit in your allocation framework — if anywhere?
- Is the problem returns, or the absence of a UK benchmark and track record your investment committee can rely on?
- Will consolidation produce allocators able to write £20m–£50m tickets into specialist credit funds, or only £250m+ cheques into the largest managers?
- With only £0.9bn of UK private debt held by Accord signatories, what would it take to make UK growth lending part of the 5% UK target?
For regulators
- Do Solvency UK matching adjustment rules leave any route for insurers to hold diversified, senior-secured growth loans?
- Do DC charge caps and daily-dealing norms make specialist credit uninvestable in practice?
For the industry, including Nighthawk
- Have UK venture debt lenders published enough loss and recovery data to earn domestic institutional trust?
- Should UK lenders pool data, as US BDCs effectively do through public filings, to create a recognised benchmark?
- Is the US interest structural, or a cyclical trade on European spreads and a weaker pound that will reverse?
Venture debt for VC-backed companies
Our facilities start from £1m, with a 36–48 month term and a 12–18 month interest-only period.